Your Year-End Financial Planning Checklist: Key Steps to Take Before December 31
The end of the calendar year brings more than holidays and cooler weather. For many people, the final quarter is one of the most financially important stretches of the year — a window of time when thoughtful action can make a meaningful difference in your tax picture, retirement savings, and overall financial trajectory.
If you've been meaning to review your finances but haven't gotten around to it yet, September is actually an ideal time to start. Waiting until late December can narrow your options and make it harder to act before key December 31 deadlines close certain windows.
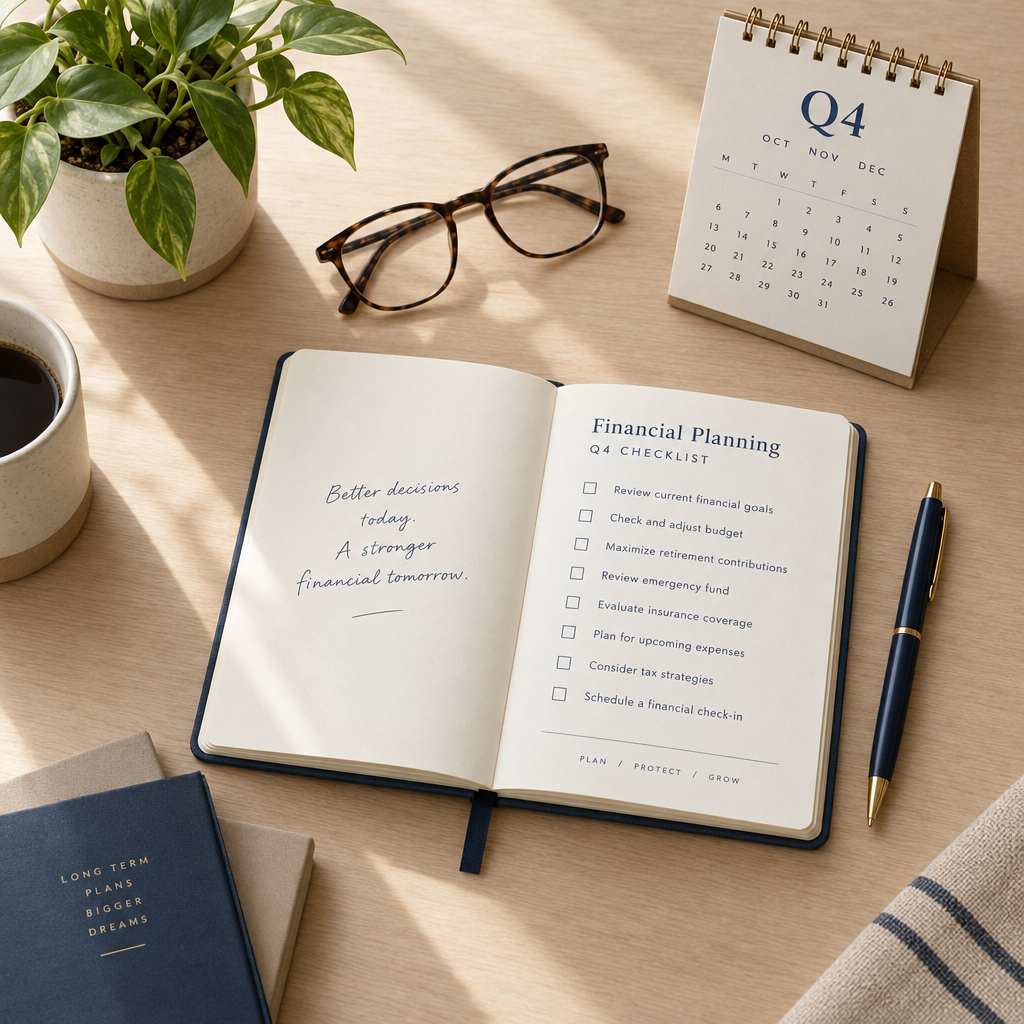
Here's a practical year-end financial planning checklist to help you focus your energy between now and the end of 2026.
Why Year-End Financial Planning Matters
Many financial decisions carry hard calendar-year deadlines. Retirement account contributions, tax-related moves, required minimum distributions, and certain deductions are all tied to December 31. Missing those deadlines can mean paying more in taxes than necessary, losing the ability to use available contribution room, or failing to meet legal distribution requirements.
Year-end planning isn't about making dramatic changes. It's about reviewing where you stand, capturing available opportunities, and setting yourself up for a stronger start to 2027.
1. Review Your Retirement Account Contributions
One of the most impactful things you can do before December 31 is confirm you're on track with contributions to tax-advantaged retirement accounts. For 2026, the IRS has set the following limits:
- 401(k), 403(b), and most 457 plans: Up to $24,500 in employee contributions
- Catch-up contributions (age 50 and older): An additional $8,000, for a total of $32,500
- Super catch-up (ages 60–63): Up to $11,250 instead of the standard catch-up, if your plan allows — bringing the total to $35,750
- Traditional and Roth IRAs: Up to $7,500 per person (or $8,600 for those age 50 and older)
If you're not on pace to reach your intended contribution level, check with your HR department or plan administrator about adjusting your deferral rate for the remaining pay periods. Even a modest increase over the last few months of the year can add up.
Important 2026 note for higher earners: A provision of the SECURE 2.0 Act now requires that catch-up contributions for individuals with prior-year FICA wages above $150,000 be made on a Roth (after-tax) basis. If this applies to you, it's worth discussing the implications with a financial and tax professional.
2. Consider Whether a Roth Conversion Makes Sense
A Roth conversion involves moving money from a traditional IRA or pre-tax retirement account into a Roth IRA. The converted amount is treated as taxable income in the year of the conversion — so the timing and size of a conversion matter.
Year-end is a natural time to evaluate whether a partial or full conversion might be worth considering, particularly if:
- Your income is lower this year than you expect in future years
- You're in a tax bracket that feels manageable for additional taxable income
- You want to reduce future required minimum distributions (RMDs)
- You're working toward a more tax-diversified retirement income strategy
Roth conversions are complex and depend heavily on individual circumstances. A financial advisor and tax professional can help evaluate whether a conversion fits your situation before December 31.
3. Take Required Minimum Distributions (RMDs) If Applicable
If you're age 73 or older, you are generally required to take a minimum distribution from your traditional IRA or 401(k) each year. Failing to take your full RMD by December 31 can trigger a significant IRS penalty — currently 25% of the amount that should have been withdrawn (reduced to 10% if corrected in a timely manner).
A few things to confirm before year-end:
- Have you taken your full 2026 RMD from all applicable accounts?
- If you inherited an IRA, separate distribution rules may apply to you depending on your relationship to the original account owner
- If you turned 73 this year, your first RMD deadline may be extended to April 1, 2027 — though taking it before December 31 may be worth discussing with an advisor to avoid two distributions landing in the same tax year
If you don't need your RMD for living expenses, you may also want to explore whether a Qualified Charitable Distribution (QCD) — which allows directing up to $108,000 directly to a qualifying charity — could be a meaningful option for your situation.
4. Assess Your Tax Picture
Tax returns aren't filed until early 2027, but the decisions you make between now and December 31 will shape your 2026 tax outcome. A few areas worth reviewing:
- Estimated tax payments: If you're self-employed or have significant investment or business income, confirm your quarterly payments are on track to avoid underpayment penalties
- Capital gains and losses: If you hold taxable investments with unrealized losses, you may want to discuss tax-loss harvesting with your advisor — selling positions at a loss to help offset realized gains elsewhere
- Charitable contributions: Cash donations to qualifying organizations are generally deductible if you itemize. Year-end is a common time to finalize charitable gifting decisions
- Flexible Spending Accounts (FSAs): Many health and dependent care FSAs carry a December 31 deadline. Check your balance and plan to use remaining funds on qualifying expenses before the year closes
These are areas where individual circumstances vary significantly. A qualified tax professional can help you evaluate your specific situation.
5. Review Your Beneficiary Designations
Beneficiary designations on retirement accounts, life insurance policies, and annuities generally override what's written in a will. That makes them one of the most important — and frequently overlooked — elements of a sound financial plan.
A year-end review is a good time to confirm:
- Your designated beneficiaries are current and reflect your actual wishes
- Major life events — marriage, divorce, the birth of a child, or the death of a named beneficiary — haven't left gaps or outdated designations in place
- Both primary and contingent beneficiaries are named on each account
- Your designations align with your broader estate and legacy planning goals
This is a high-impact task that takes relatively little time and can prevent significant complications for your family later.
6. Check In on Your Investment Allocation
Markets move throughout the year. What started as a balanced investment allocation in January may have shifted meaningfully by the fall — particularly if one asset class significantly outperformed or underperformed others.
Year-end is a reasonable time to review whether your current allocation still aligns with:
- Your long-term financial goals
- Your risk tolerance — how comfortable you are with the possibility of short-term loss
- Your time horizon — how many years before you expect to need these funds
- Any meaningful changes in your financial situation since the beginning of the year
This isn't about reacting to short-term market movements. It's about making sure your portfolio structure still reflects what you intended it to reflect. Rebalancing decisions can carry tax implications in taxable accounts, so coordinating with both a financial advisor and a tax professional is worth doing.
7. Look Ahead to 2027
Year-end planning isn't only about closing out 2026 — it's about setting yourself up well for the year ahead. Before December 31, consider:
- Does your savings rate or monthly budget need an adjustment heading into 2027?
- Are there major life events on the horizon — a job change, home purchase, retirement, or a child starting college — that should shape your planning priorities?
- Does your emergency fund feel appropriately funded for your current situation and risk exposure?
- Are there estate planning documents — wills, trusts, healthcare directives, or powers of attorney — that need to be updated or created?
None of these need to be fully resolved by December 31, but identifying them now gives you a clearer runway and more time to plan thoughtfully.
Don't Wait Until December
One of the most common year-end planning mistakes is simply waiting too long. Some moves — such as adjusting a 401(k) contribution rate, completing a Roth conversion, or updating an estate document — take time to process and coordinate. Others, like tax-loss harvesting, require careful thought and sequencing rather than last-minute decisions.
Starting your review now gives you the breathing room to make informed, deliberate choices rather than rushed ones.
Ready to Talk Through Your Year-End Checklist?
Not every item on this list will apply equally to your situation. The goal isn't to do everything — it's to do the right things for where you are in your financial life right now.
If you'd like to talk through how these year-end considerations fit into your broader financial plan, the team at Eden Advisory Services is here to help. We work with individuals, families, and business owners to make thoughtful, well-informed financial decisions — not just at year-end, but throughout every stage of the financial journey.
Schedule a consultation with Eden Advisory Services and let's make sure 2026 finishes strong.
Disclaimer: This article is for general educational purposes and should not be considered individualized investment, tax, or legal advice. Financial decisions should be evaluated based on your individual circumstances and, when appropriate, in consultation with qualified financial, tax, or legal professionals. Contribution limits and tax rules referenced are based on IRS guidance current as of the date of this publication and are subject to change.