When Should You Claim Social Security? A Planning Guide for 2026
One Decision. A Lifetime of Impact.
For most people approaching retirement, few choices carry more long-term weight than deciding when to begin collecting Social Security benefits. Claim too early, and you may lock in a permanently reduced benefit. Wait too long, and you leave years of income on the table. And unlike most financial decisions, this one generally cannot be undone.
The right answer depends on your health, your financial situation, your spouse's circumstances, and how Social Security fits into your broader retirement income picture. This guide walks through the key claiming ages, the tradeoffs involved, and the questions worth thinking through before you decide.
Understanding Full Retirement Age in 2026
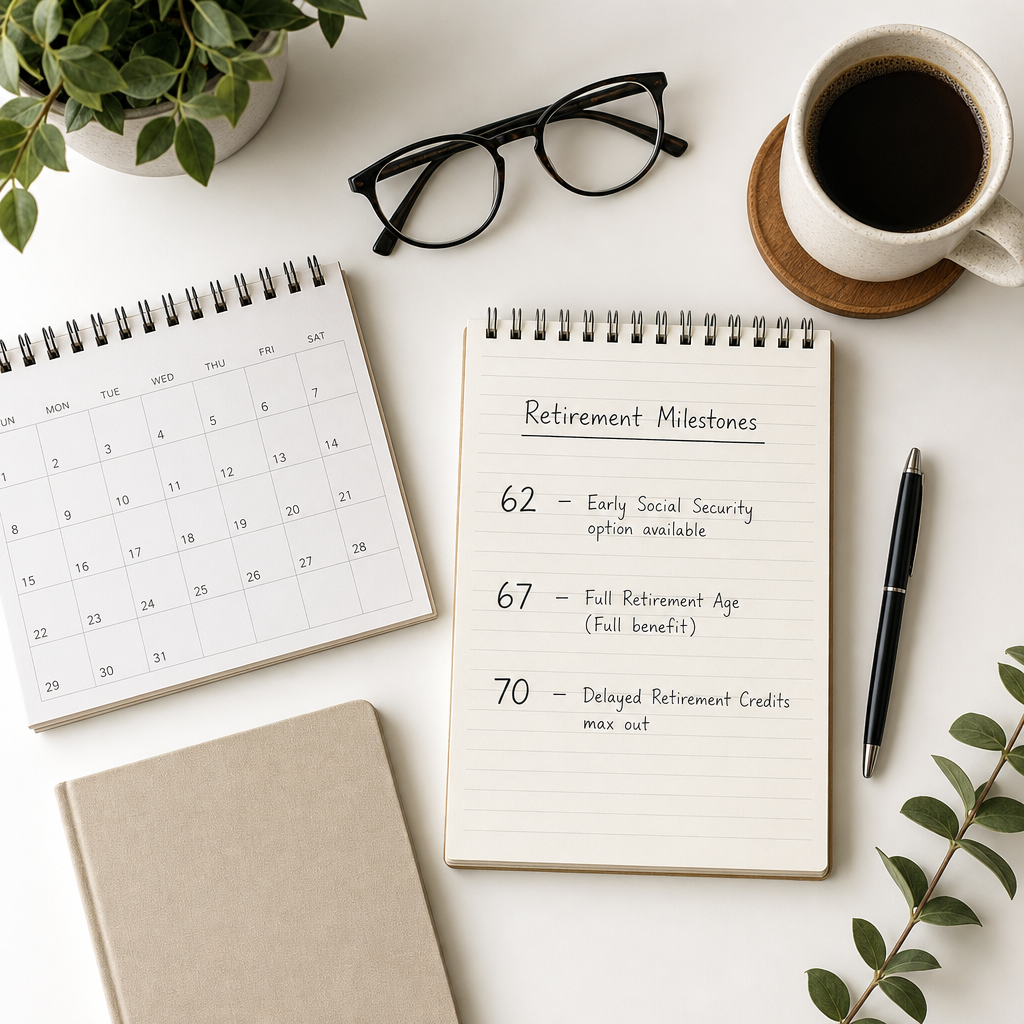
Your Full Retirement Age (FRA) is the age at which you qualify to receive your complete, unreduced Social Security retirement benefit — the amount based on your full earnings history. For anyone born in 1960 or later, that age is 67. The gradual phase-in of FRA from 65 to 67 — which began for those born after 1937 — is now complete.
If you were born between 1955 and 1959, your FRA falls somewhere between 66 and 2 months and 66 and 10 months. You can verify your specific FRA on the Social Security Administration's website at ssa.gov.
Knowing your FRA is the starting point for every claiming decision, because all benefit adjustments — reductions for early claiming and credits for delayed claiming — are calculated relative to that age.
Your Three Main Claiming Windows
Claiming at 62: The Earliest Option
Age 62 is the earliest you can begin collecting Social Security retirement benefits. For many people, the appeal is straightforward: income sooner rather than later.
But early claiming comes at a cost. If your FRA is 67, claiming at 62 reduces your monthly benefit by up to 30 percent — permanently. That reduction stays with you for the rest of your life, and it also affects any spousal or survivor benefits that may eventually be calculated off of your record.
Early claiming may make sense in certain situations — for example, if you have a serious health condition that affects your life expectancy, or if you genuinely need the income to meet basic living expenses and have no other reasonable alternative. But it is rarely the right choice simply because you are eligible.
Claiming at Your Full Retirement Age: The Baseline
Waiting until your FRA means collecting your full, unreduced benefit. For those born in 1960 or later, that means waiting until 67.
Claiming at FRA provides a clean baseline: no reductions, no additional credits. Your monthly benefit reflects exactly what your earnings record entitles you to. For many people — particularly those in good health who have other income sources to bridge the gap — waiting until FRA represents a meaningful improvement over early claiming.
Claiming at 70: Maximizing Your Monthly Benefit
Every year you delay Social Security past your FRA, your benefit grows by approximately 8 percent through what the SSA calls Delayed Retirement Credits. These credits accumulate until age 70, after which there is no additional benefit to waiting.
Claiming at 70 instead of 62 can result in a monthly benefit that is roughly 76 percent higher than what you would have received at 62. Over a long retirement, that difference can be substantial — particularly if you live into your 80s or beyond.
The tradeoff, of course, is that you receive no Social Security income during the years between your FRA and age 70. That means you will need other resources — savings, a pension, investment income, or a working spouse — to cover living expenses in the interim.
Key Factors That Influence the Decision
Your Health and Life Expectancy
The longer you live, the more likely delayed claiming is to pay off in total lifetime benefits. A commonly used benchmark is the break-even age — the point at which the higher monthly benefit from waiting surpasses the cumulative payments you would have received by claiming earlier.
For many people, the break-even point between claiming at 62 versus 67 falls somewhere in the mid-to-late 70s. If you are in good health with family longevity on your side, delaying may serve you well. If serious health challenges are a factor, earlier claiming may make more financial sense. This is a deeply personal calculation, and one worth discussing with a financial professional who understands your full picture.
Spousal and Survivor Benefits
For married couples, the Social Security decision becomes even more layered. A spouse may be eligible for up to 50 percent of the higher earner's FRA benefit as a spousal benefit. Survivor benefits — which the remaining spouse would receive after the other passes — are based on the deceased spouse's actual benefit at the time of death.
This means the higher earner's claiming decision has a direct impact on potential survivor income for decades. Couples where one spouse significantly out-earned the other often find it worthwhile to have the higher earner delay claiming as long as possible, even while the lower earner claims earlier to bring in some income.
The Impact of Working While Collecting
If you claim Social Security before your FRA and continue working, the SSA's earnings test may temporarily reduce your benefit if your income exceeds certain annual thresholds. Once you reach FRA, the earnings test no longer applies — you can work and collect your full benefit without penalty.
This is an important consideration for anyone thinking about a phased retirement or part-time work in their early 60s.
How Social Security Fits Into Your Broader Retirement Income Plan
Social Security was designed to be one component of retirement income — not the whole picture. How much you need from Social Security depends on what other income sources you have: retirement accounts, pension income, investment portfolios, real estate, or business income.
If your other income sources are strong, you may have more flexibility to delay and maximize your Social Security benefit. If Social Security will need to carry a heavier share of your retirement income, the timing decision becomes even more consequential.
Tax Considerations
Depending on your total income in retirement, a portion of your Social Security benefit may be subject to federal income tax. For individuals with combined income above $25,000 and married couples above $32,000, up to 85 percent of Social Security benefits may be taxable under current IRS rules. The interplay between Social Security income and your other withdrawals — from traditional IRAs, 401(k)s, or other accounts — is worth understanding before you finalize a claiming strategy.
Questions Worth Asking Before You Decide
- What is my Full Retirement Age, and what is my estimated benefit at each claiming age?
- How does my health and family history of longevity factor into this decision?
- Does my spouse have their own Social Security record, and how do our decisions interact?
- What other income sources will I have in retirement, and how large a role does Social Security need to play?
- Do I plan to continue working part-time before my FRA?
- Have I considered how Social Security income may interact with my tax situation?
- What happens to my spouse's income if I pass away first?
There Is No One Right Answer — But There Is a Right Process
Claiming Social Security is not a one-size-fits-all decision. The ideal timing depends on your individual health, your household income picture, your spouse's situation, and your longer-term financial goals. What works well for one person may not be the right approach for someone in a different situation.
What matters most is making this decision thoughtfully — with a clear understanding of how each option affects your lifetime income, your household's financial security, and your retirement plan as a whole.
You can estimate your own benefit at various claiming ages using the SSA's online tools at ssa.gov.
This article is for general educational purposes and should not be considered individualized investment, tax, or legal advice. Social Security rules are complex and your specific benefit amounts and eligibility may vary. Financial decisions should be evaluated based on your individual circumstances and, when appropriate, with qualified financial, tax, or legal professionals.
Ready to Think Through Your Retirement Income Strategy?
Social Security is just one piece of a thoughtful retirement plan. At Eden Advisory Services, we help individuals and families understand how their decisions today connect to their financial security for decades to come.
If you'd like to talk through how Social Security fits into your broader retirement and wealth plan, we'd welcome the conversation. Schedule a consultation with Eden Advisory Services and let's discuss what makes sense for your situation.