What Is a Fiduciary Financial Advisor — And Why It Matters for Your Money
When you hand someone the responsibility of helping guide your financial future, a straightforward question deserves a clear answer: Is this person required to put my interests first?
The answer depends on whether your financial advisor operates under a fiduciary standard. This single distinction can meaningfully affect the advice you receive, the products recommended to you, and the confidence you feel in your financial plan.
Here is what the fiduciary standard means, how it differs from other standards, and what to look for when evaluating a financial professional.
What Does "Fiduciary" Mean?
The word fiduciary comes from the Latin word for trust. In a financial context, a fiduciary is someone who is legally and ethically obligated to act in your best interest — not their own, and not their employer's.
A fiduciary financial advisor must:
- Prioritize your interests above their own financial gain
- Disclose any conflicts of interest that could influence their recommendations
- Provide advice that is suitable for your specific situation, not just advice that is generally acceptable
- Be transparent about compensation, including how they are paid and by whom
This is a meaningful legal obligation — not just a marketing claim. Advisors bound by the fiduciary standard can face regulatory and legal consequences for violating it.
The Fiduciary Standard vs. the Suitability Standard
Not every financial professional is held to the fiduciary standard. Historically, many broker-dealers and commission-based advisors were held to a lower bar: the suitability standard.
Under the suitability standard, a financial professional only needs to recommend products that are suitable for a client based on general factors like age, income, and risk tolerance. That is a lower bar than acting in the client's best interest.
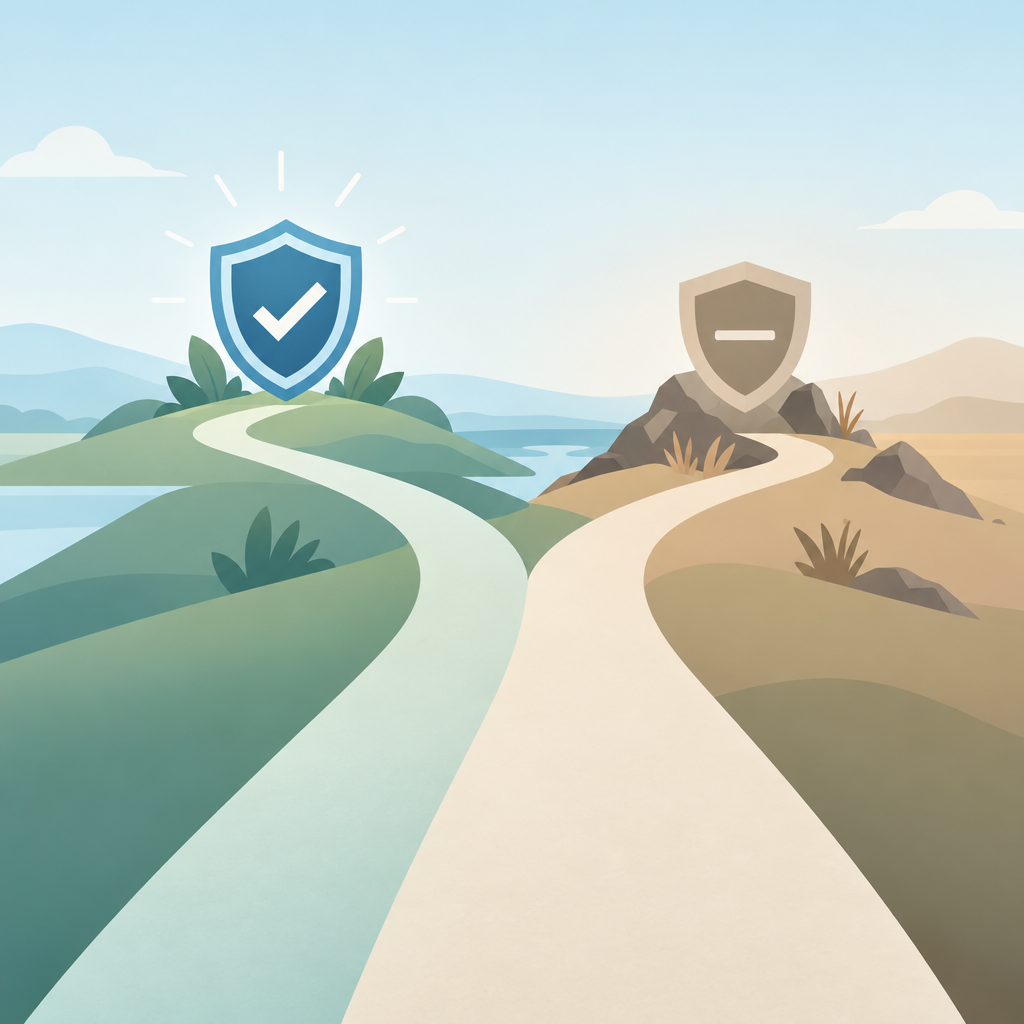
Here is a simplified illustration of the difference:
| Standard | What It Requires | Who It Typically Applies To |
|---|---|---|
| Fiduciary | Must act in the client's best interest | Registered Investment Advisers (RIAs) |
| Best Interest (Reg BI) | Recommendations must be in the client's best interest, with disclosure requirements | Broker-dealers (SEC Regulation Best Interest, 2020) |
| Suitability | Recommendations must be suitable based on general profile | Some broker-dealer contexts prior to Reg BI |
It is worth noting that in 2020, the SEC introduced Regulation Best Interest (Reg BI), which raised the standard for broker-dealers beyond simple suitability. However, the RIA fiduciary standard is generally considered more comprehensive — particularly around ongoing obligations and conflict-of-interest management.
A Practical Example
Imagine two investment products offer similar exposure to the same asset class. One pays the advisor a higher commission. A fiduciary advisor would be expected to recommend the option that is better for you, even if it pays less to them. Under a suitability standard alone, the higher-commission product might be recommended as long as it is not clearly inappropriate for your situation.
This distinction matters most when financial products with significantly different cost structures are involved — such as insurance products, annuities, or certain mutual funds.
Who Is Legally Considered a Fiduciary?
Under U.S. securities law, Registered Investment Advisers (RIAs) — whether firms or individual investment adviser representatives — are held to a fiduciary standard when providing investment advice. This is established under the Investment Advisers Act of 1940 and enforced by the SEC and, for smaller advisers, state securities regulators.
RIAs are required to:
- Provide advice in the client's best interest
- Seek best execution on transactions
- Make full and fair disclosure of all material conflicts of interest
- Avoid making misleading statements
You can verify whether an individual or firm is a registered investment adviser using FINRA's BrokerCheck tool at brokercheck.finra.org or the SEC's Investment Adviser Public Disclosure (IAPD) database at adviserinfo.sec.gov.
Certain other financial professionals — including those who serve as trustees or manage ERISA retirement plan assets — may also carry fiduciary responsibilities under different laws.
How Fiduciary Advisors Are Typically Compensated
Compensation structure is one of the most important things to understand when evaluating a financial advisor, because it can directly affect potential conflicts of interest.
Fee-Only
Fee-only advisors are compensated exclusively by their clients — typically through flat fees, hourly rates, or a percentage of assets under management (AUM). They do not earn commissions from product sales. Because their income does not depend on which products they recommend, fee-only arrangements are often associated with reduced conflicts of interest.
Fee-Based
Fee-based advisors charge clients directly and may also earn commissions or other compensation from third parties when certain products are sold. This does not automatically make an advisor untrustworthy, but it does create potential conflicts that should be clearly disclosed.
Commission-Based
Commission-based advisors earn compensation primarily when financial products are purchased. They may or may not be fiduciaries depending on their registration and the nature of the advice they provide.
Regardless of the compensation model, a fiduciary advisor is obligated to disclose how they are paid and any material conflicts of interest that could influence their recommendations. This information is typically found in a document called Form ADV, which registered investment advisers are required to provide to clients and file publicly with the SEC.
Questions to Ask a Financial Advisor Before You Begin
If you are evaluating a financial professional, these questions can help you understand their obligations and how they operate:
- Are you a fiduciary? Are you a fiduciary at all times, or only in certain situations? Some advisors wear multiple hats and may not be acting as a fiduciary in every transaction.
- How are you compensated? Ask directly whether they earn commissions, fees, or both — and from whom.
- What conflicts of interest do you have? A transparent advisor should be able to answer this clearly.
- Are you registered as an investment adviser? Ask for their Form ADV, which contains background information, services offered, fees, and disclosed conflicts of interest.
- What is your investment philosophy? Understanding how they approach financial decisions can help you assess whether the relationship is a good fit.
- How do you communicate with clients? Knowing how often and in what format you will receive updates helps set realistic expectations.
Getting clear answers to these questions upfront can help you build a more informed, trusting relationship with any financial professional.
Why the Fiduciary Standard Matters for Long-Term Financial Planning
Financial planning is not a one-time transaction. It is an ongoing relationship that may span decades — through major life events, market cycles, career changes, and retirement. The quality and consistency of the advice you receive over that time period can have a meaningful cumulative effect on your financial outcomes.
When a financial advisor is bound by a fiduciary standard, you have a clearer framework for what to expect: that their recommendations are made with your interests as the primary consideration. That clarity can make it easier to have honest conversations, ask difficult questions, and make decisions with greater confidence.
This does not mean every non-fiduciary advisor gives poor advice or that every fiduciary advisor gives perfect advice. But understanding the standard your advisor is held to is an important part of making an informed choice.
A Few Important Caveats
The fiduciary label alone is not a guarantee of excellent advice, strong performance, or a good personal fit. When choosing a financial professional, consider:
- Experience and qualifications — Look for relevant credentials, experience working with clients in similar situations, and a clear explanation of their investment philosophy.
- Transparency — Does the advisor communicate clearly about fees, risks, and the reasoning behind recommendations?
- Fit — Does this advisor understand your goals, values, and financial circumstances?
- Track record and regulatory history — Use FINRA BrokerCheck and the SEC's IAPD database to review any regulatory actions or complaints.
Choosing a financial advisor is a significant decision that deserves careful thought — not just a quick look at a title.
The Bottom Line
Understanding what a fiduciary is — and asking whether your financial advisor operates under that standard — is one of the most valuable steps you can take before entering any advisory relationship. It helps you ask better questions, set clearer expectations, and make a more informed decision about who you trust with your financial future.
Financial decisions are rarely one-size-fits-all. If you'd like to talk through how to evaluate your financial options and what a thoughtful advisory relationship might look like for your situation, schedule a consultation with Eden Advisory Services.
This article is for general educational purposes and should not be considered individualized investment, tax, or legal advice. Financial decisions should be evaluated based on your individual circumstances and, when appropriate, with qualified financial, tax, or legal professionals. All regulatory information referenced is based on publicly available guidance as of the date of publication.