What Does Wealth Management Actually Include?
If you've ever searched for a financial advisor and come across the term wealth management, you may have wondered exactly what that means — and whether it's something designed only for the ultra-wealthy, or something that could be genuinely useful to you.
The term gets used broadly, and that can make it confusing. In practice, wealth management is a comprehensive approach to financial guidance that brings together multiple areas of your financial life under one coordinated strategy. It's not just about investing — and understanding what's actually included can help you make a more informed decision about the kind of financial relationship you're looking for.
Wealth Management vs. Financial Planning: What's the Difference?
Financial planning typically focuses on helping you set goals, build a budget, prepare for retirement, and create a roadmap for your financial future. It's foundational and valuable at nearly every stage of life.
Wealth management generally encompasses financial planning — and layers additional, more integrated services on top of it. A wealth management relationship often involves ongoing coordination across investments, taxes, estate planning, insurance, and long-term goals, with the advisor serving as a central point of contact who helps connect all those pieces.
Think of financial planning as building the map, and wealth management as actively navigating the journey over time — adjusting as your life, goals, and circumstances change.
What a Comprehensive Wealth Management Relationship Can Include
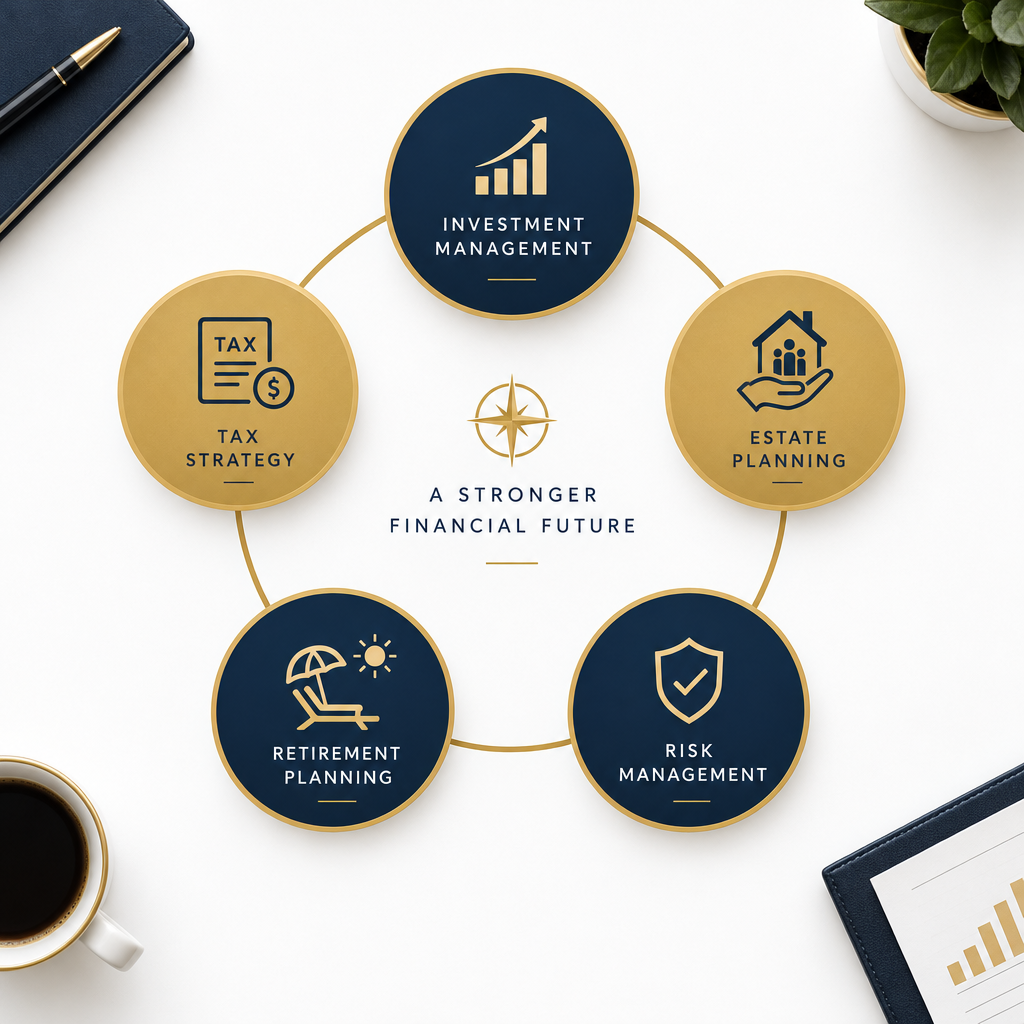
While every firm and every client relationship is different, a thorough wealth management engagement typically addresses several interconnected areas:
1. Investment Management
This is often the most visible component of wealth management. It involves building and managing a portfolio of investments — stocks, bonds, funds, and other asset classes — aligned with your goals, time horizon, and comfort with risk.
Key concepts in investment management include:
- Asset allocation: How your investments are divided across different categories (such as equities, fixed income, and cash) to balance growth potential with risk.
- Diversification: Spreading investments across multiple holdings to reduce the impact of any single investment underperforming.
- Risk tolerance: Your personal comfort level with market fluctuations — which should shape how your portfolio is constructed.
- Ongoing monitoring and rebalancing: Reviewing your portfolio over time and adjusting when your allocation drifts from your intended targets due to market movements.
A wealth manager doesn't just set up a portfolio and step away. Ongoing oversight and adjustment — in response to life changes, market conditions, and evolving goals — is a core part of the relationship.
2. Retirement Planning
A central goal for many people working with a wealth manager is building enough financial security to one day stop working — or at least to have the option to. Retirement planning within a wealth management context typically involves:
- Determining how much you may need saved by retirement based on your anticipated lifestyle and expenses
- Choosing and maximizing the right savings vehicles, such as 401(k) plans, IRAs, Roth IRAs, and other accounts
- Planning how you'll generate income in retirement from your savings, Social Security, and other sources
- Understanding required minimum distributions (RMDs) — the minimum withdrawals the IRS requires from certain tax-deferred accounts beginning at age 73 — and how to plan around them
- Sequencing withdrawals in a tax-efficient manner to make your savings last
Retirement planning isn't a one-time conversation. It evolves as you move through different life stages, and your strategy at 40 may look quite different from your strategy at 60.
3. Tax Strategy and Coordination
Taxes are one of the largest long-term costs associated with building and preserving wealth. A good wealth management relationship incorporates proactive thinking about tax efficiency — not just at tax season, but throughout the year.
This can include considerations around:
- Tax-advantaged accounts: Understanding which accounts offer tax deductions, tax-deferred growth, or tax-free withdrawals — and using them strategically
- Tax diversification: Holding assets across taxable, tax-deferred, and tax-free accounts to give you more flexibility in retirement
- Capital gains awareness: Being mindful of when gains are realized and how that affects your tax picture
- Coordination with tax professionals: A wealth manager may work alongside your CPA or tax advisor to ensure your investment and planning decisions support your overall tax strategy
It's important to note that investment advisors are not tax professionals, and tax advice should come from a qualified CPA or tax attorney. However, a thoughtful wealth manager considers the tax implications of financial decisions and can help coordinate your overall picture.
4. Estate and Legacy Planning
Estate planning is the process of deciding how your assets will be managed, protected, and transferred — to your heirs, a charity, or others — during your lifetime and after you're gone.
Within a wealth management relationship, estate planning considerations can include:
- Reviewing and updating beneficiary designations on retirement accounts, life insurance policies, and other accounts
- Understanding how wills, trusts, and powers of attorney work together
- Planning for the potential costs and delays of probate
- Using tools like irrevocable trusts or special needs trusts when appropriate for your family's situation
- Coordinating with estate attorneys to ensure your plan is legally sound and properly executed
Estate planning isn't only for people with large estates. Anyone with assets, dependents, or specific wishes about what happens to their financial life deserves a thoughtful plan in place.
5. Risk Management and Insurance Review
Building wealth matters — but protecting it matters just as much. Risk management within a wealth management relationship often involves reviewing whether you have appropriate coverage in place to protect against major financial disruptions, including:
- Life insurance to provide for dependents or a surviving spouse
- Disability income coverage in case you're unable to work
- Long-term care considerations as you approach retirement
- Property and liability coverage
The goal isn't to sell insurance for its own sake — it's to identify meaningful gaps between your current coverage and what would be needed to protect your financial plan if something unexpected happened.
6. Goal-Based Financial Planning
Underlying all of these components is an ongoing conversation about what you actually want your financial life to look like. Wealth management isn't just about accumulating the largest possible number — it's about building a financial life that supports your goals, values, and priorities.
That might include:
- Funding a child's or grandchild's education
- Purchasing a second home or investment property
- Supporting a cause or charitable organization
- Transitioning out of a business
- Creating financial independence for yourself or your family
A wealth manager helps you connect the dots between these goals and the practical financial steps needed to pursue them.
Who Can Benefit from a Wealth Management Relationship?
Wealth management is not exclusively for multi-millionaires. While some firms do set high asset minimums, many financial advisors — including those who take a planning-first approach — work with people at a wide range of stages and account sizes.
You may benefit from a more comprehensive wealth management approach if:
- You have multiple financial accounts or assets that aren't coordinated
- You're approaching retirement and need help building an income strategy
- You own a business and want to connect your business finances with your personal plan
- You've recently experienced a major life event — marriage, divorce, inheritance, or a career change
- You're concerned about taxes, estate planning, or protecting your family's financial future
- You want a trusted long-term financial relationship rather than one-time advice
Questions Worth Asking a Prospective Wealth Manager
If you're considering working with a wealth management professional, a few questions can help you understand whether they're the right fit:
- What services are included in your relationship? Investment management only, or a broader planning relationship?
- How do you approach coordination across investments, taxes, and estate planning?
- How often will we meet or communicate?
- How are you compensated? Fee-only, fee-based, or commission-based arrangements each carry different implications.
- What's your philosophy around long-term planning?
There's no single right answer to any of these questions — but understanding them helps you make a more informed choice.
The Value of a Coordinated Approach
One of the core advantages of a genuine wealth management relationship is that all of these areas — investments, retirement, taxes, estate planning, insurance, and goals — are considered together, not in isolation. A decision that looks smart from an investment standpoint might have unintended tax or estate consequences. A plan that looks financially conservative might leave meaningful risks unaddressed.
When someone is looking at your full financial picture, those disconnects are more likely to be caught — and addressed — before they become costly problems.
A Note on the Language of Wealth Management
Because "wealth management" is used so broadly in the financial services industry, it's worth doing your homework when evaluating any firm or advisor who uses the term. Ask specifically what services are included, how the advisor is compensated, and what kind of ongoing relationship you can expect. The label matters less than the substance of the relationship you're actually entering into.
This article is for general educational purposes and should not be considered individualized investment, tax, or legal advice. Financial decisions should be evaluated based on your individual circumstances and, when appropriate, with qualified financial, tax, or legal professionals.
Financial decisions are rarely one-size-fits-all. If you'd like to talk through how a comprehensive wealth management approach might fit your goals, schedule a consultation with Eden Advisory Services. We work with individuals, families, and business owners across all stages of their financial journey — and we'd be glad to start a conversation.